“The French are giving the State a gift by putting their money into it”: the government wants to fill our Livret A books and yet it is not the best idea to finance the economy
If the Livret A allows, mainly, to finance social housing, other investments also make it possible to finance long-term projects, requiring greater risk-taking.
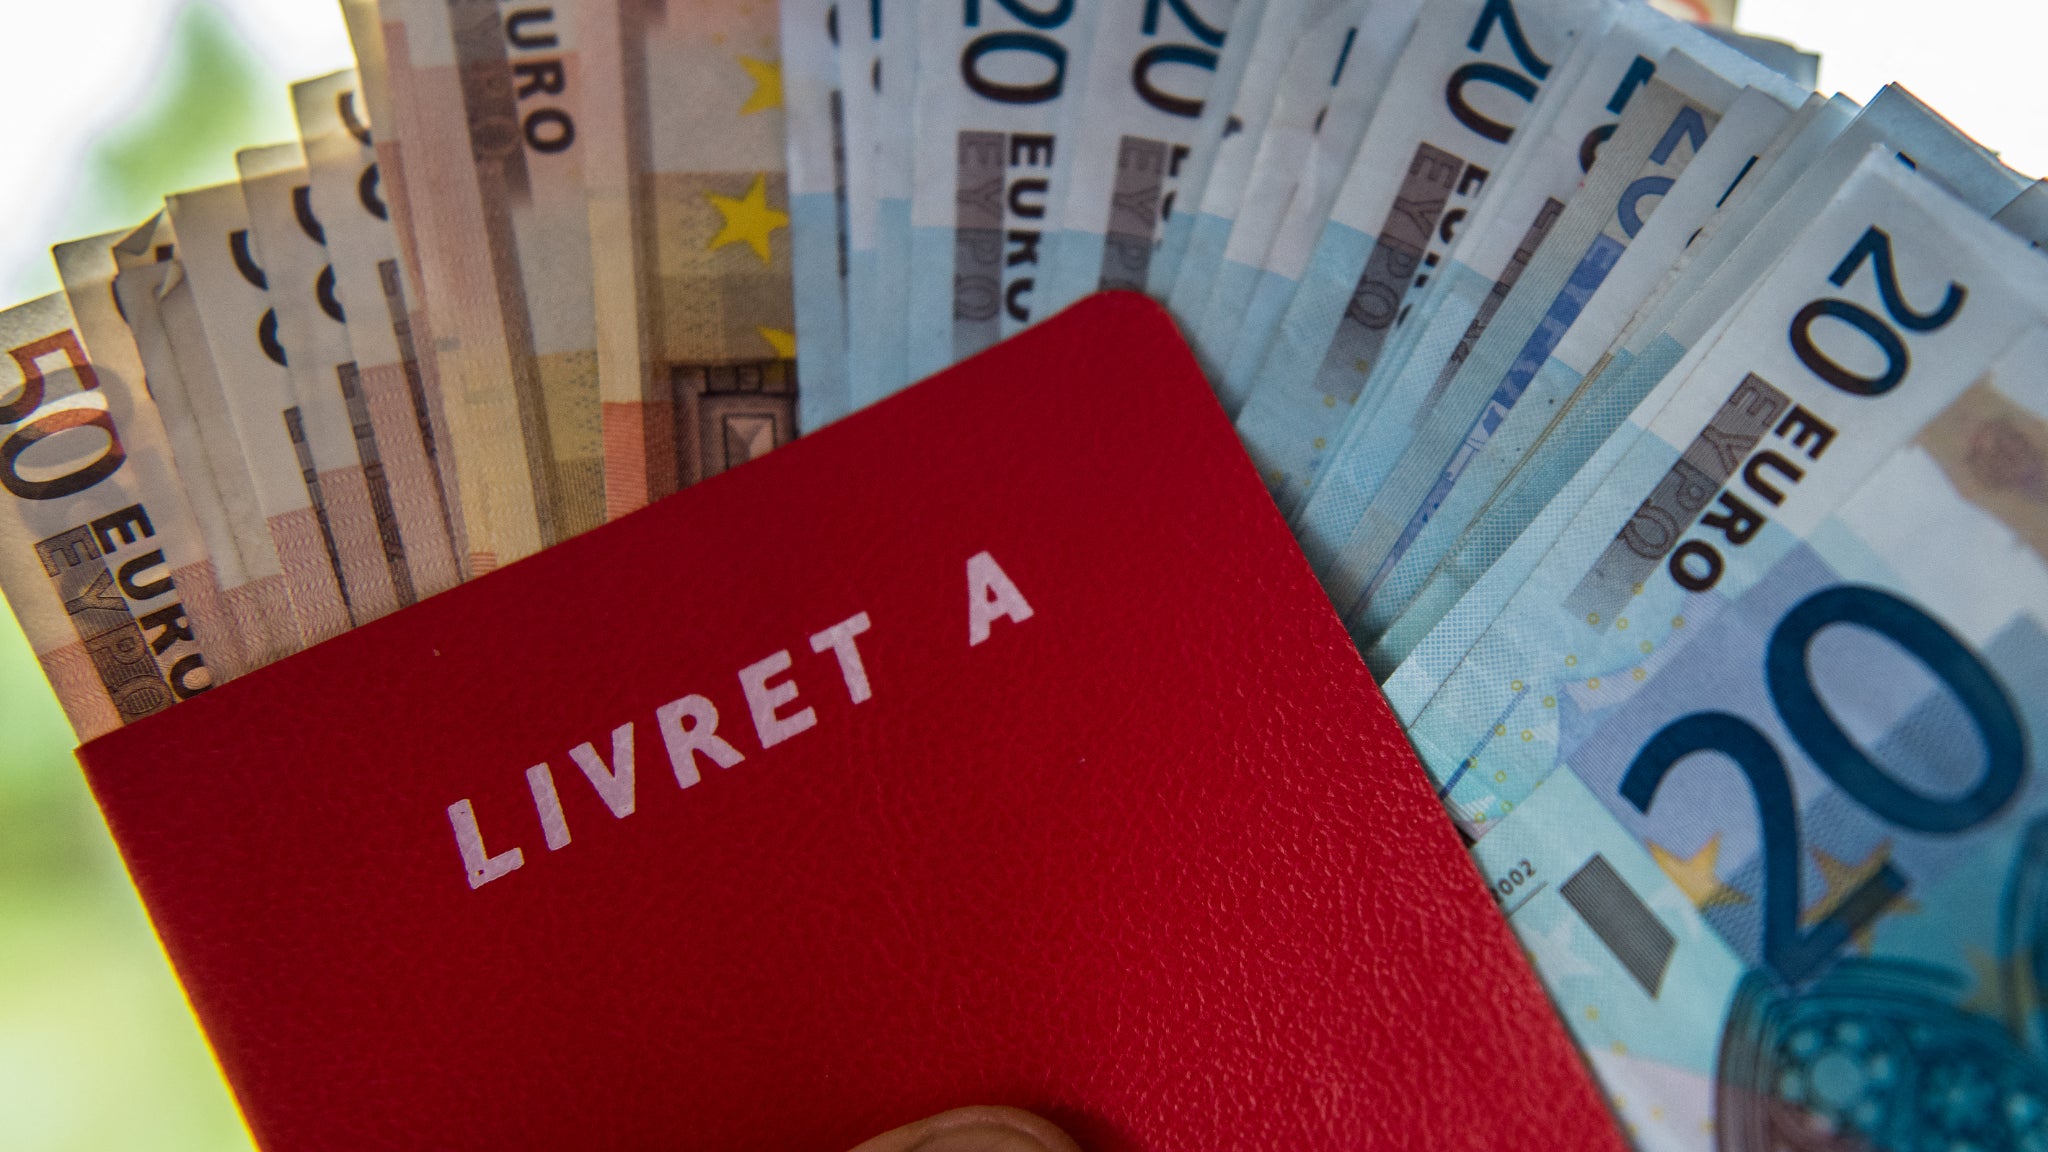
Is the Livret A the best way to finance long-term investments? This savings product, whose remuneration rate is currently set at 1.7%, is held by 83% of French people. At the end of September 2026, its outstanding amount amounted to 442 billion euros.
What explains its popularity, beyond its liquid nature, is that the French know what their invested money is used for. Today, the Caisse des Dépôts savings fund centralizes 60% of the sums collected from the Livret A, the Sustainable Development Booklet (LDDS) and the Popular Savings Booklet (LEP), with the banks collecting the rest (40%) of the funds. At the end of 2025, this savings fund managed 453.3 billion euros in collections divided between 244.9 billion euros in long-term loans and 208.4 billion euros in financial assets.
Of the long-term loans, 203.4 million euros make it possible to finance social housing and urban policy, 29 billion euros the local public sector (nurseries, schools, hospitals, etc.) and 10.5 million euros the ecological and energy transition. In February 2027, the ceiling of Livret A, currently at 22.
950 euros, will be increased in a range from 25,000 to 30,000 euros, as confirmed by Prime Minister Sébastien Lecornu.
His rate of pay should also be increased. The government's objective is to increase the amount placed in this savings account to finance more long-term projects, including future nuclear reactors. However, its very success raises questions.
“Its outstanding assets far exceed the needs of social housing and part of these savings would benefit from being directed towards long-term investments,” points out Matéis Mouflet, market analyst at XTB France, citing in particular life insurance, the retirement savings plan (PER) or the stock savings plan (PEA). “Not the only savings product” In reaction to the upcoming increase in the Livret A ceiling, Emmanuel Moulin, declared this week on BFM Business that this investment was not the “only savings product” to consider for long-term financing. This is a savings "which is very liquid, so what we will try to do is rather to have long-term savings to finance both businesses, innovation, and also finance retirement", explained the governor of the Bank of France.
In this regard, he cited the retirement savings plan (PER), held by 12.3 million French people and whose outstanding assets today amount to 150 billion euros. Launched in 2019, the PER allows savers to finance their retirement. It is also described by the General Directorate of the Treasury as a “tool serving the financing of the economy, particularly the European economy”.
More than 60% of PER assets directly finance companies, "including more than 5 billion euros in unlisted assets, investment capital in SMEs and ETIs, infrastructure funds, shares of listed SMEs/ETIs", specifies the organization. For experts, the money placed in a PER being blocked until retirement (except in some cases of early release such as the purchase of the main residence), it would better finance long-term projects than the Livret A, the funds of which remain available at any time for the saver. “All long-term savings placed in bonds, particularly via life insurance and PER euro funds, supports the demand for French debt and contributes to containing long-term rates,” explains Matéis Mouflet in reaction to the comments of the governor of the Bank of France.
“This makes financing the deficit less expensive and reduces dependence on foreign investors, who today hold more than half of the State's negotiable debt. The downside is that in the event of a debt crisis, French savers would be more exposed,” he explains. Today, however, France cannot hope to significantly reduce its debt thanks to French investments.
To date, it has reached 3.595 billion euros. “A gift to the State” Accepting more risks than regulated savings accounts, the PER would therefore be more useful for financing the real economy.
But it also has its limits according to the XTB expert. On the one hand, the tax advantage at entry is proportional to the marginal tax bracket: it is low for a low-tax household and mainly benefits high incomes. On the other hand, the sums are taxed on exit, while the Livret A is exempt.
Likewise, unlike a Livret A which allows you to know where, in part, your money is going, the saver has less visibility on this subject, particularly with a PER in managed management. Likewise, several mechanisms allow you to subscribe to it (from the euro fund, through the units of account, the FCPEs, etc.) which may imply that this product will not necessarily directly finance a long-term project. For Matéis Mouflet, the problem of financing long-term projects in France comes mainly from the behavior of the French with their money.
The latter prefer to turn to less risky investments, which finance the economy less. The saver “makes a sort of gift to the State by placing his money in the Livret A”. However, this type of investment will not really help him to ensure better days in retirement.
Machine-translated from French
Not cross-checked yet
Only BFM Business reports this story so far. We show it as a single source until another newsroom confirms it.
- BFM Business16 Nov, 05:55
| Publisher BFM Business (established tier) | +76 |
| Detailed summary | +2 |
| Total | 78 |
Method: reports are grouped by the words of their headline and summary; each newsroom counts once; figures are read from the reports as published. Nothing here is written by an AI.